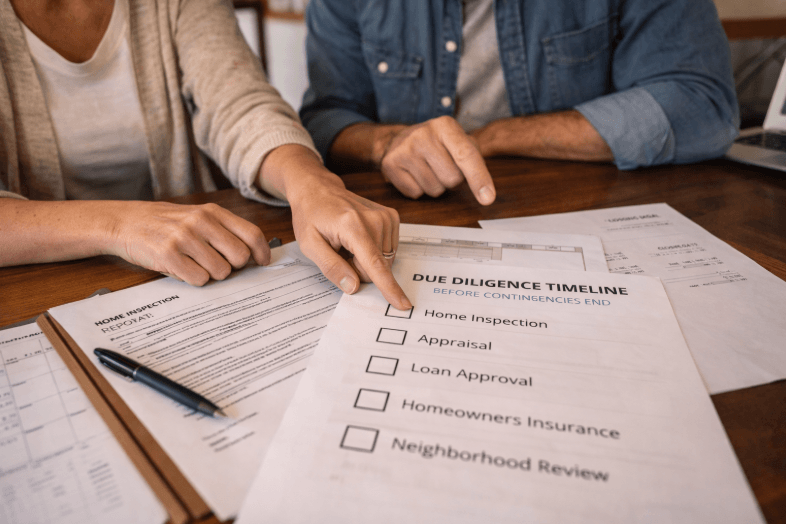
A buyer who has four months to review your company reads like a researcher. A buyer who has three weeks reads like a bouncer. I’ve sat on both sides of that table, and the difference isn’t the buyer’s personality. It’s the calendar. When a deal gets compressed, every binder, spreadsheet, and scanned contract gets judged on a single question: can we verify this fast enough to sign?
That’s the diligence clock, and it’s the thing most sellers prepare for last. On a relaxed timeline, buyers ask about your lease renewal history and dig into board minutes from 2019. On a compressed one, they triage. They skim, they flag, they ask for confirmation instead of reading. If your documents can’t survive that shift, the price moves and the deal gets ugly.
What the clock actually measures
Diligence isn’t a single event, it’s a countdown with a few hard milestones. There’s the exclusivity window, the lender’s underwriting slot, the regulatory review, and the closing date everyone has already promised someone else. Miss one and the whole chain slips. Buyers know this, so they build a mental order of operations: financials first, contracts second, everything else if there’s time.
I’ve watched a seller lose negotiating ground simply because the revenue recognition schedule was buried in a folder named “2021 misc.” Nobody questioned the numbers once they surfaced. The buyer just used the delay to ask for a holdback. The clock doesn’t care about fairness. It rewards speed of access.
One more thing worth naming: the regulatory layer. If your deal touches an industry the FTC watches, the review timeline is partly out of everyone’s hands, and you can read more about how merger review works before buyers start asking pointed questions. Getting ahead of that conversation keeps you from discovering late that your own files raised the flag.
Why compressed deals read differently
Here’s the plain version. Under deadline pressure, buyers switch from reading to scanning. Scanning has its own logic, and it’s brutal for messy sellers.
A scanner looks for three things: is the document the one I asked for, does it match what the seller told me, and does the date line up with the rest of the story? If any answer is fuzzy, the item becomes a flagged question rather than a confirmed fact. Flagged questions need follow up. Follow up needs time you don’t have.
So the practical goal isn’t a prettier folder structure. It’s eliminating the moments where a buyer has to come back and ask you something you already knew.
Build the answer before the question
Every deal produces the same thirty or forty questions, just in different words. Buyers want to know who owns what, when contracts renew, which clients can leave on short notice, and whether any obligations survive past closing. You can predict almost all of it.
So write it down. Not a sales pitch, an internal memo. One line per known risk, what the document shows, and where it lives. I’d pick a plain one to three page summary over a polished deck every single time, because the summary answers the clock and the deck just postpones it.
Two details that consistently pay off:
- Version control. Buyers trust the file that matches what’s in the official record. After a merger, the legal record of filings is what everyone cross-references, so label drafts clearly and never let two versions of the same contract circulate.
- Dates that agree with each other. If your revenue schedule says a customer renewed in March and the contract says April, that discrepancy costs you a week of back and forth over nothing.
A short walkthrough that changes the math
Picture a services company heading into a sale. The founders have everything, technically. Financial statements, client contracts, insurance certificates, the operating agreement. It’s all in a shared drive organized by who scanned it, which is to say, not organized at all.
Three weeks into diligence, the buyer’s counsel asks for the two largest client agreements and the amendment from last fall. It takes the seller’s controller a full day to find the amendment and another half day to confirm it’s the executed version. The buyer, watching this, quietly revises the integration risk assessment upward.
Now run the same deal with a proper diligence workspace where documents are indexed by category, tagged by counterparty, and permissioned so the buyer sees exactly what’s been released and when. The amendment surfaces in minutes. Nobody revises anything upward. The seller’s credibility, which is really the only currency in a tight process, stays intact.
This is where modern data rooms earn their keep. Not as storage, but as a way to hand the clock back to yourself instead of the buyer. Every search the buyer doesn’t have to ask you for is a day you didn’t spend.
Mapping documents to deal stage
Not everything belongs in front of the buyer on day one. Releasing too much too fast creates new questions; releasing too little stalls the process. A rough staging order helps.
| Deal stage | What goes out | Why now |
|---|---|---|
| Preliminary review | Summaries, org structure, headline financials | Lets buyers decide fast without deep exposure |
| Exclusivity | Contracts, leases, IP, employment agreements | This is when the real reading happens |
| Confirmatory | Consents, lien releases, closing certificates | Only useful once terms are settled |
If you’re early in the process, the groundwork matters more than the tooling. Public companies file the same core disclosures on a schedule, and the regulatory filings they produce are a decent model for what a buyer expects to see documented and dated. You don’t need their volume, just their discipline.
See also: How to Improve Business Performance
Common mistakes that cost real money
Clean up the revenue recognition memo first. It’s the most scrutinized document in any deal and the least likely to be updated. After that, I’d look at your customer concentration data, because a buyer seeing one client at forty percent of revenue starts doing math you won’t like under time pressure.
Then check how long it takes an outsider to find your three largest contracts without your help. If the answer is “they’d have to ask,” you’ve got work to do before diligence starts, not during it.